How to Finance a Barndominium Kit
You can finance a barndominium kit. It just takes a little more homework than buying an existing house, because many lenders are still getting used to steel homes.
The Usual Path: A Construction-to-Permanent Loan
Most people building a new barndominium use a construction-to-permanent loan (also called a one-time close loan). It pays out in stages, or "draws," as the build moves along, then converts into a regular mortgage when the home is done. A two-time close loan does the same job with a separate construction loan and mortgage.
Where to Look
- Local banks and credit unions, especially in rural areas where barndominiums are common. They know the local market and often keep loans on their own books.
- Lenders that specialize in rural or non-traditional homes.
- USDA and VA programs can work in qualifying situations, but the home still has to pass the appraisal and program rules.
The Appraisal Problem, and How to Handle It
Lenders base the loan on an appraisal, and appraisers need comparable sales. In areas with few barndominium sales, that can lead to a low value. To help:
- Bring a complete plan set and a detailed budget. Our full construction plans help here.
- Ask the lender which appraisers they use and whether they've valued barndominiums before.
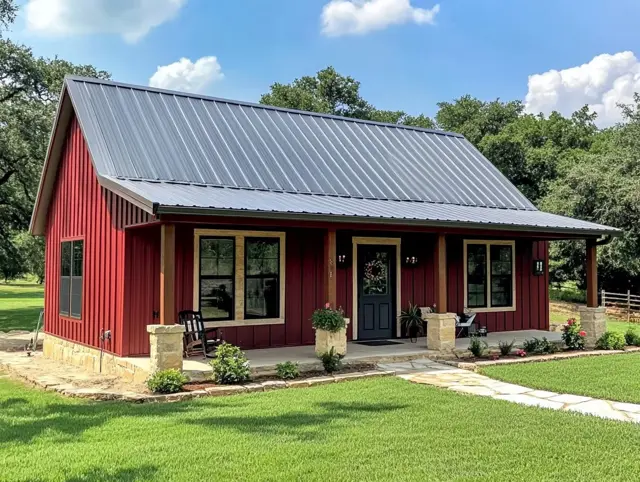
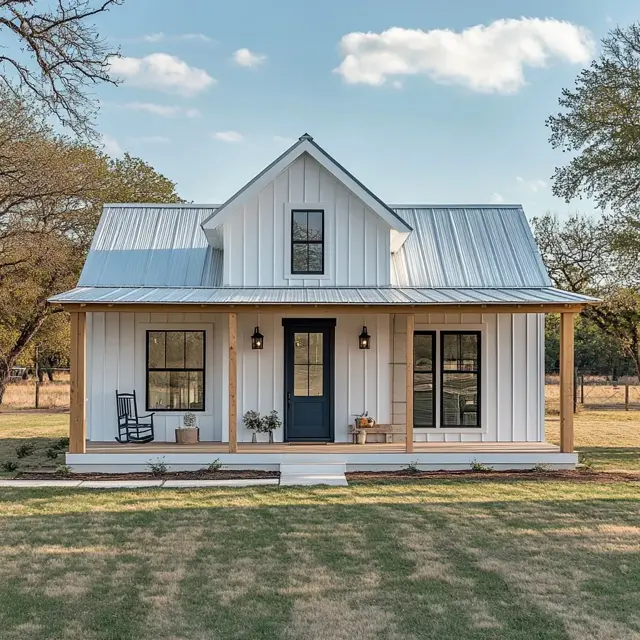
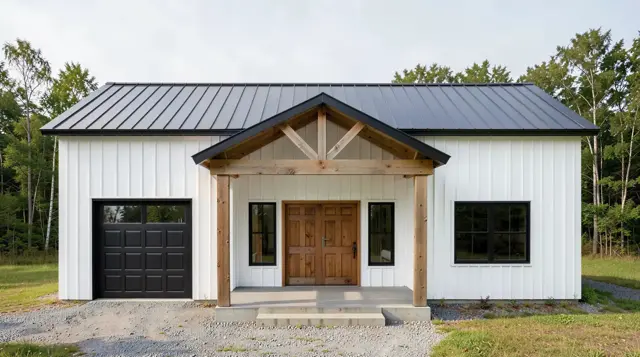
- Design and finish the home like a house: a real porch, windows, a residential-looking entry.
- Keep the shop in proportion to the house, since lenders sometimes treat big shops differently.
What Lenders Usually Want to See
- A full set of construction plans (this is where buying the plans first pays off)
- Your kit quote and a line-item construction budget
- Your builder's information, or owner-builder approval if they allow it
- Land ownership or a land purchase contract
Ready to start? Pick a kit, buy the plans, and you'll have the documents most lenders ask for.
Ready to Price Your Kit?
Browse 159 red iron and cold-formed steel barndominium kits, each with full plans and an up-front kit estimate.
Browse Barndominium Kits